
JUMBO CONSTRUCTION FINANCING
Construction Financing for Higher-Value and Custom Homes
Building a custom or higher-value home can require financing beyond the limits and structure of standard construction loan programs.
Jumbo construction loans are designed for qualified borrowers whose building projects require larger loan amounts. Depending on the program, you may be able to build on land you own or buy land as part of the transaction. Financing may also cover eligible home construction costs.
Jumbo construction loans vary by lender. Compare the full loan structure, costs, and terms.
Platinum Lending Solutions compares jumbo construction loans from multiple lenders for borrowers in Oregon and Washington. We review the property, project and your finances, along with your long-term plans.
Higher-Value Custom-Home Financing
Larger projects may require a closer review of your equity, cash and reserves. Land value, builder approval, the appraisal, fund releases and permanent financing also matter.
What Is a Jumbo Construction Loan?
A jumbo construction loan funds a new home when the loan amount exceeds standard conforming construction limits.
Like other construction loans, the financing must account for a home that does not yet exist in its completed form.
The lender therefore evaluates not only the borrower but also the proposed project, which may include:
- Land or building site
- Builder or general contractor
- Architectural plans and specifications
- Construction contract
- Detailed project budget
- Construction timeline
- Expected completed value
- Draw schedule
Depending on the lender and project, you may need more equity, cash, and reserves for a jumbo construction loan.
When Might You Need a Jumbo Construction Loan?
Jumbo construction financing may be appropriate when the amount required to build the home exceeds the limits or parameters of available conforming construction programs.
This can occur with:
Higher-Value Custom Homes
Larger Construction Budgets
High-Cost Building Locations
Properties With Significant Land Value
Larger or More Complex Custom-Home Projects
Construction Requiring a Larger Permanent Mortgage
The price of the land alone does not determine whether jumbo financing is required.
Review the land, total project cost and loan amount together. The expected completed value, your contribution and permanent mortgage also affect the options.
Building on Land You Already Own
Many custom-home borrowers purchase or own their building site before construction financing is arranged.
If you already own the land, its value and any available equity may play an important role in structuring the construction loan.
The lender will generally evaluate:
- Current land value
- How and when the land was acquired
- Existing liens, if any
- Proposed construction
- Total project cost
- Expected completed value
Some programs may count land equity toward your required investment. The rules depend on the loan and transaction.
Lenders count land equity differently. Review how your land will be treated before estimating how much more cash you need.
Can You Finance the Land and Construction Together?
Potentially.
Certain jumbo construction programs may allow qualified borrowers to purchase the building site and finance construction as part of the same overall transaction.
Loan rules vary. If possible, review construction financing before you buy the land.
An early review can show whether the land, budget, and your cash contribution fit an available loan.
How Jumbo Construction Financing Works
Although the specific process varies by lender and program, jumbo construction financing generally involves several stages.
01
Borrower Qualification
The lender evaluates the borrower’s overall financial profile.
Depending on the program, this may include:
• Income and employment
• Credit
• Assets
• Existing obligations
• Available funds
• Liquidity
• Reserves
• Other real estate owned
Large projects can cost more than expected as work progresses. Lenders may pay close attention to the cash and reserves you have available.
02
Project Review
The lender evaluates what is being built and whether the proposed project meets its construction lending requirements.
This may include the plans, specifications, construction contract, builder, budget, timeline, and property.
03
Appraisal
The appraisal may estimate the finished home’s value. The loan program sets the requirements.
04
Closing
Once the borrower, property, builder, and project satisfy the applicable requirements, the construction financing closes.
05
Construction Draws
Construction funds are generally released in stages. Work must progress and meet the lender’s draw rules.
06
Completion and Permanent Financing
Once construction is complete, the next step depends on whether the financing was structured as construction-only or construction-to-permanent financing.
Jumbo Construction-to-Permanent Loans
Jumbo construction financing may potentially be structured as construction-to-permanent financing.
A construction-to-permanent structure combines the construction phase and permanent mortgage within one overall loan structure.
For a higher-value custom home, review both loan phases carefully. Your choice affects the building loan and a potentially large long-term mortgage.
Alternatively, some borrowers may use construction-only financing and arrange separate permanent financing when the home is completed.
Neither structure is automatically better.
The construction terms, permanent mortgage terms, costs, rate structure, lock provisions, flexibility, and borrower’s longer-term strategy should be evaluated together.
Down Payment and Equity Requirements
There is no single down payment requirement for every jumbo construction loan.
Required borrower equity can vary based on factors including:
• Loan amount
• Total project cost
• Land value
• Existing land equity
• Expected completed value
• Borrower qualifications
• Liquidity and reserves
• Property characteristics
• Loan structure
• Lender requirements
For borrowers who already own valuable land, available equity may affect the amount of additional cash required.
Each lender may count equity differently. Compare actual loan options before estimating your cash needs.
Liquidity and Reserve Requirements
Larger construction projects can require borrowers to demonstrate substantial financial resources beyond the funds needed at closing.
Depending on the program, the lender may require reserves or other available liquidity.
These requirements can be particularly important with custom construction because project costs and timelines can change.
Strong income and credit may not be enough on their own. Cash and reserve requirements can affect which jumbo construction programs you qualify for.
For that reason, the entire financial profile should be reviewed early in the planning process.
Builder Approval
The builder is an important component of jumbo construction financing.
Each lender may set rules for the builder or general contractor. The review may cover experience, licenses, insurance and finances. Prior projects and contracts may also be reviewed.
The exact approval process varies by lender.
Check the lender’s builder rules before finalizing financing. This is especially useful for a complex custom home.
Choosing a builder first may limit your loan options if that builder does not meet lender rules.
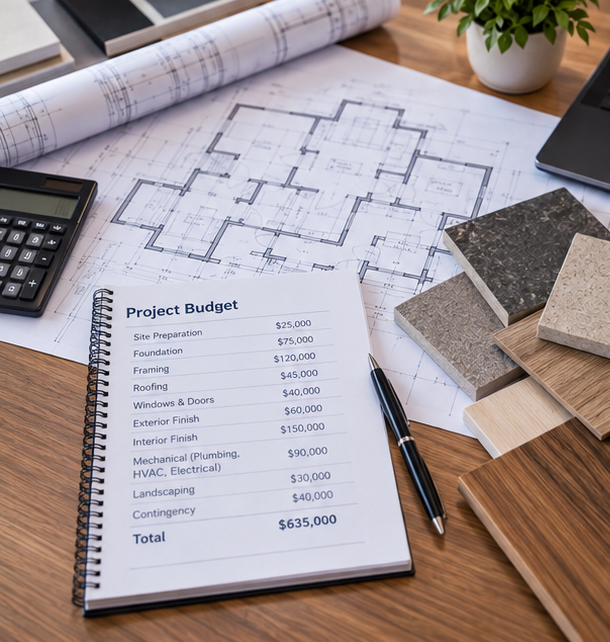
Plans, Specifications, and Construction Budget
Jumbo construction lenders generally need a detailed understanding of what is being built and what the project is expected to cost.
Documentation may include:
- Architectural plans
- Specifications
- Construction contract
- Detailed cost breakdown
- Labor and material estimates
- Allowances
- Construction timeline
- Project contingencies
The more complex the project, the more important it becomes for the construction plans, contract, budget, appraisal, and financing to align.
Major project changes may affect an approved loan. Talk to the lender before making those changes.
How Is a Jumbo Construction Home Appraised?
A custom home under construction cannot be evaluated in the same manner as an already completed property.
Depending on the program, the appraisal may estimate the finished home’s value. It may use the site, plans, specifications, proposed work and relevant market data.
Highly customized homes can present additional valuation considerations because there may be fewer directly comparable completed properties.
The completed appraised value can be an important part of determining the final financing structure, particularly when the project cost and requested loan amount are substantial.
How Are Construction Funds Released?
Jumbo construction funds are typically paid out in stages, called draws. They are not all released at closing.
As designated stages of construction are completed, funds may be requested and released according to the lender’s procedures.
Depending on the program, this may involve:
01
Completion of a designated construction stage
02
Submission of a draw request
03
Inspection or verification of completed work
04
Satisfaction of applicable draw requirements
05
Release of approved construction funds
The draw schedule should be understood by both the borrower and builder before construction begins.
A large build may need substantial funds at each stage. Review draw timing and procedures with your builder before work starts.
Interest Rates and Rate-Lock Considerations
Rate structures can vary significantly among jumbo construction programs.
Depending on the loan, there may be different provisions governing the construction period, permanent financing, and when or how a permanent mortgage rate can be established.
Construction can take many months, making rate-lock provisions and the eventual permanent financing particularly important considerations.
A borrower should therefore evaluate more than the initial construction rate.
Compare the full costs and terms of both loan phases. Review the construction loan, permanent mortgage, and rate-lock rules.
Why Comparing Jumbo Construction Lenders Matters
Jumbo construction lending is not necessarily standardized from one lender to another.
Different lenders may have different approaches to:
• Maximum loan amounts
• Required borrower equity
• Treatment of land equity
• Liquidity and reserves
• Builder approval
• Property characteristics
• Construction budgets
• Draw procedures
• Construction timelines
• Rate structures
• Permanent financing
• Closing requirements
A project that does not fit one lender’s construction program may potentially fit another lender differently.
This is where working with an independent mortgage brokerage can be particularly useful.
Platinum Lending Solutions can review your project with multiple lenders. We compare the loan structures available for your transaction.
Jumbo Construction Loans vs. Standard Construction Loans
Both standard and jumbo construction financing can be used to build a new home, and both may involve project approval, builder requirements, appraisals, budgets, inspections, and construction draws.
The primary distinction is the size and structure of the financing required.
Higher loan amounts and larger custom projects may also result in different requirements for borrower equity, reserves, liquidity, property valuation, and permanent financing.
If your project does not require jumbo financing, explore construction loan options →
Start With Financing Before Finalizing a High-Value Build
With a large custom-home project, financing should be evaluated early.
Before purchasing land or finalizing construction plans, understanding the available financing can help establish:
- Realistic total project financing
- Potential cash and equity requirements
- Treatment of land equity
- Liquidity and reserve requirements
- Builder requirements
- Construction budget parameters
- Draw procedures
- Construction-to-permanent options
- Permanent mortgage considerations
- Rate and lock provisions
An early review may reveal financing limits while you still have time to adjust. You may be able to change the land purchase, budget or loan structure.
Jumbo Construction Loans in Oregon & Washington
Higher-value construction projects can vary considerably based on location, land characteristics, property design, construction costs, builder, loan amount, and borrower financial profile.
As an independent mortgage brokerage serving Oregon and Washington, Platinum Lending Solutions can evaluate jumbo construction financing through multiple lending sources.
Our role is to help borrowers compare available programs, understand the requirements, and determine which financing structure may align with both the custom-home project and longer-term mortgage strategy.
Jumbo Construction Loan FAQs
What makes a construction loan jumbo?
A construction loan is generally considered jumbo when the financing required exceeds the parameters of available conforming construction financing. The applicable structure depends on the loan amount, program, property, and transaction.
Can I use a jumbo construction loan if I already own the land?
Potentially. Existing land and available equity may be considered when structuring certain jumbo construction loans.
Can I finance the land purchase and construction together?
Certain programs may allow qualified borrowers to acquire land and finance construction as part of the same overall transaction. Availability and requirements vary by lender.
Does my land equity count toward the down payment?
Potentially. How existing land equity is calculated and applied toward the financing depends on the lender, loan program, property, and transaction.
Do jumbo construction loans require larger reserves?
Reserve and liquidity requirements vary by program and borrower. Because jumbo construction involves larger loan amounts and potentially significant project costs, financial reserves and liquidity can be important qualification considerations.
Does the builder need to be approved?
Many jumbo construction lenders establish requirements for builders or general contractors. The approval process varies by lender and should be addressed early.
How are construction funds distributed?
Construction funds are generally released through a series of draws as designated stages of work are completed and applicable lender requirements are satisfied.
How is a custom home appraised before it is built?
Depending on the program, the appraisal may evaluate the property’s expected completed value using the land, plans, specifications, proposed improvements, and applicable market data.
Can a jumbo construction loan be a one-time-close loan?
Potentially. Some jumbo construction financing may be available using a construction-to-permanent structure. Program availability and terms vary by lender.
Can I lock my permanent mortgage rate during construction?
Possibly. Rate-lock provisions vary considerably between construction lenders and loan structures and should be evaluated when comparing programs.
Planning a Higher-Value Custom Home?
Financing a custom home involves more than determining whether you qualify for a particular loan amount.
The land, construction budget, builder, completed value, borrower equity, liquidity, construction financing, and eventual permanent mortgage all need to work together.
Platinum Lending Solutions can help you evaluate jumbo construction loan options across multiple lending sources and understand the financing requirements before you commit to the project.
Have Questions About Your Jumbo Construction Loan Options?
Tell us a little about the land, proposed home, builder, construction budget, and financing you are considering. We can help you evaluate potential jumbo construction options and determine what steps to consider next.
Related case study: $1.6M Jumbo Construction Loan Case Study
More Construction and Jumbo Loan Guidance
Compare the overall building process in our Construction & Renovation Loans hub, including Construction-to-Permanent Loans. If you are purchasing an existing higher-priced home rather than building, our Jumbo Loans guide explains how loan limits and borrower qualifications differ from construction financing.
