FIX & FLIP INVESTOR LOANS
Short-Term Financing for Investment Property Acquisition and Renovation
A successful fix-and-flip project starts with finding the right property — but the financing can be just as important to the outcome.
Fix and flip loans are short-term, business-purpose loans designed for real estate investors purchasing properties to renovate and resell. Unlike traditional residential renovation mortgages, investor fix-and-flip financing is generally structured around the investment property, renovation plan, project economics, and exit strategy.
Depending on the program, financing may help cover both the acquisition of the property and eligible renovation costs.
Platinum Lending Solutions helps real estate investors throughout Oregon and Washington evaluate fix-and-flip financing from multiple lending sources and compare loan structures based on the property, project, experience, capital requirements, and investment strategy.
Investment-Focused Financing
PROPERTY ACQUISITION
Finance an investment property intended for renovation and resale.
RENOVATION
Eligible improvement costs may be incorporated into certain financing structures.
EXIT STRATEGY
The project is generally structured around renovation, resale, and repayment of the short-term loan.
What Is a Fix & Flip Loan?
Short-term business-purpose financing designed around an investment property, renovation project, and defined exit strategy.
A fix and flip loan is generally short-term financing used by a real estate investor to acquire a property, complete improvements, and sell the renovated property for a profit.
These loans are different from traditional mortgages because the property is being acquired as an investment rather than as the borrower’s primary residence.
They are also different from consumer renovation loans.
A renovation mortgage may be designed for someone purchasing or improving a home they intend to occupy or hold with long-term mortgage financing. Fix-and-flip financing is designed specifically around an investment project with a defined business purpose and exit strategy.
What Can a Fix & Flip Loan Finance?
Depending on the lender and program, fix-and-flip financing may potentially be used for:
Acquisition
Acquisition of an investment property
Renovation
Renovation and rehabilitation costs
Major Repairs
Properties requiring substantial repairs
Cosmetic Work
Cosmetic renovation projects
Major Improvements
Structural or major improvement projects
Difficult Property Condition
Properties that may not qualify for conventional financing in their current condition
Repeat Projects
Repeat investment projects for experienced real estate investors
Loan structures and eligible costs vary considerably by lender.
The property, renovation scope, borrower experience, available capital, and anticipated exit strategy can all affect which financing options are available.
How Fix & Flip Financing Works
Although programs vary, fix-and-flip financing generally considers both the purchase of the investment property and the planned renovation.
1 — Property Acquisition
The lender evaluates the property being purchased, the acquisition price, and the proposed investment.
2 — Renovation Plan
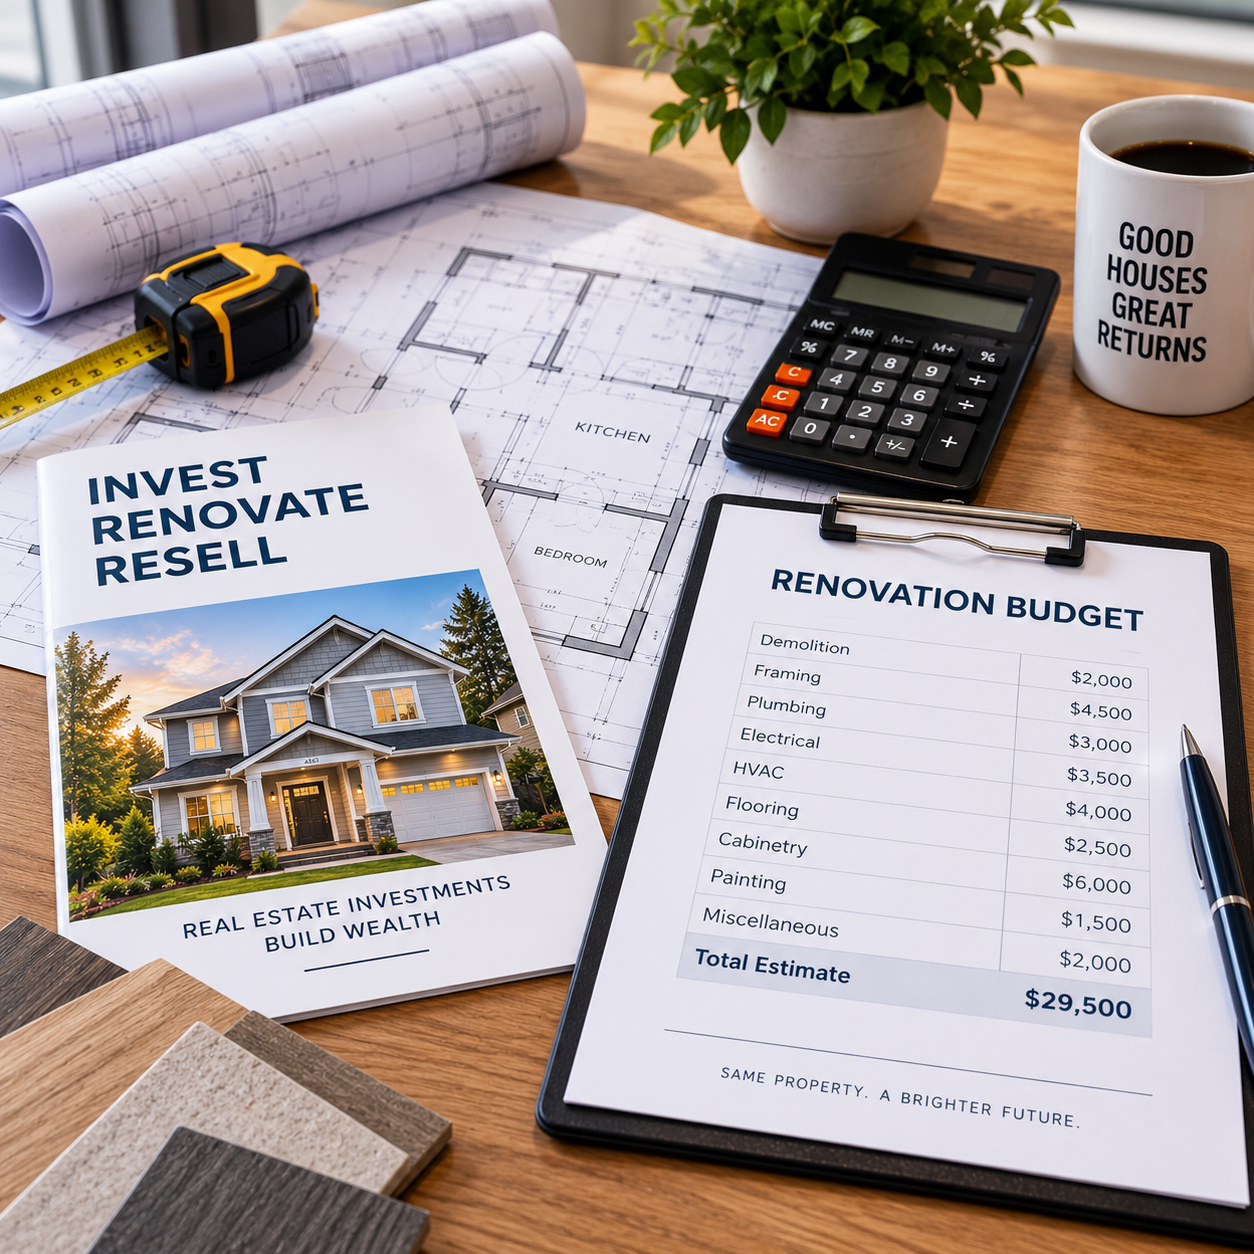
The investor typically provides a scope of work and renovation budget outlining the improvements planned for the property.
3 — Property Valuation
Depending on the program, the lender may consider both the property’s current value and its anticipated value after the renovations are completed.
4 — Investor Qualifications
The lender may evaluate factors such as the investor’s credit, available liquidity, assets, prior real estate or renovation experience, and ability to complete the proposed project.
5 — Renovation Funds
Funds designated for construction or renovation are typically controlled by the lender and released through draws as eligible work is completed.
6 — Exit Strategy
Because fix-and-flip financing is short term, the lender will want to understand how the loan is expected to be repaid.
For a traditional flip, the anticipated exit is generally the sale of the renovated property.
Purchase Price, Renovation Budget, and After-Repair Value
Three numbers can play an important role in evaluating a fix-and-flip project:
1
Purchase Price
The amount being paid to acquire the property.
2
Renovation Budget
The anticipated cost of completing the improvements necessary to execute the investment plan.
3
After-Repair Value (ARV)
The estimated value of the property after the proposed renovations have been completed.
Fix-and-flip lenders may evaluate the relationship between these figures when determining how much they are willing to finance.
This is one of the major differences between investor financing and a traditional residential mortgage.
The lender is not simply evaluating the property as it exists today. The overall project and expected completed value may also influence the financing structure.
How Much Cash Does an Investor Need?
There is no single down payment or cash requirement that applies to every fix-and-flip loan.
The investor’s required contribution can depend on factors including:
• Purchase price
• Current property value
• Renovation budget
• Expected after-repair value
• Investor experience
• Credit profile
• Available liquidity and reserves
• Property type
• Loan amount
• Lender guidelines
Some lenders may place greater emphasis on investor experience or project leverage than others.
Comparing multiple programs can therefore be particularly valuable when structuring a fix-and-flip transaction.
How Are Renovation Funds Released?
When renovation costs are included in the financing, those funds are generally not handed to the investor in full at closing.
Instead, renovation funds may be held and released through a draw process as work is completed.
Depending on the lender, the process may include:
1
Completing a designated portion of the renovation.
2
Requesting a draw.
3
Providing documentation or allowing an inspection of completed work.
4
Receiving approved funds.
5
Continuing to the next phase of the renovation.
Draw procedures vary by lender and should be understood before closing.
For an investor managing contractors, cash flow, and project timelines, the draw process can materially affect how the project operates.
Does Investor Experience Matter?
It can.
Some lenders offer different terms or qualification standards based on an investor’s prior experience purchasing, renovating, or selling investment properties.
An experienced investor with successfully completed projects may have access to financing structures that differ from those available to someone completing a first flip.
However, being a first-time investor does not necessarily mean financing is unavailable.
The property, project, borrower qualifications, liquidity, and lender guidelines all need to be evaluated together.
Can First-Time Investors Get Fix & Flip Financing?
Potentially.
Some lenders will consider investors completing their first fix-and-flip project, although qualification requirements and financing terms may differ from programs designed for experienced investors.
A first-time investor should be prepared to present a well-developed project, including:
• Property information
• Purchase terms
• Detailed renovation budget
• Scope of work
• Contractor information, when applicable
• Available funds and reserves
• Proposed project timeline
• Exit strategy
Starting the financing discussion before making assumptions about leverage or renovation funding can help establish a realistic acquisition budget.
What Types of Properties May Qualify?
Eligible property types vary by lender and program.
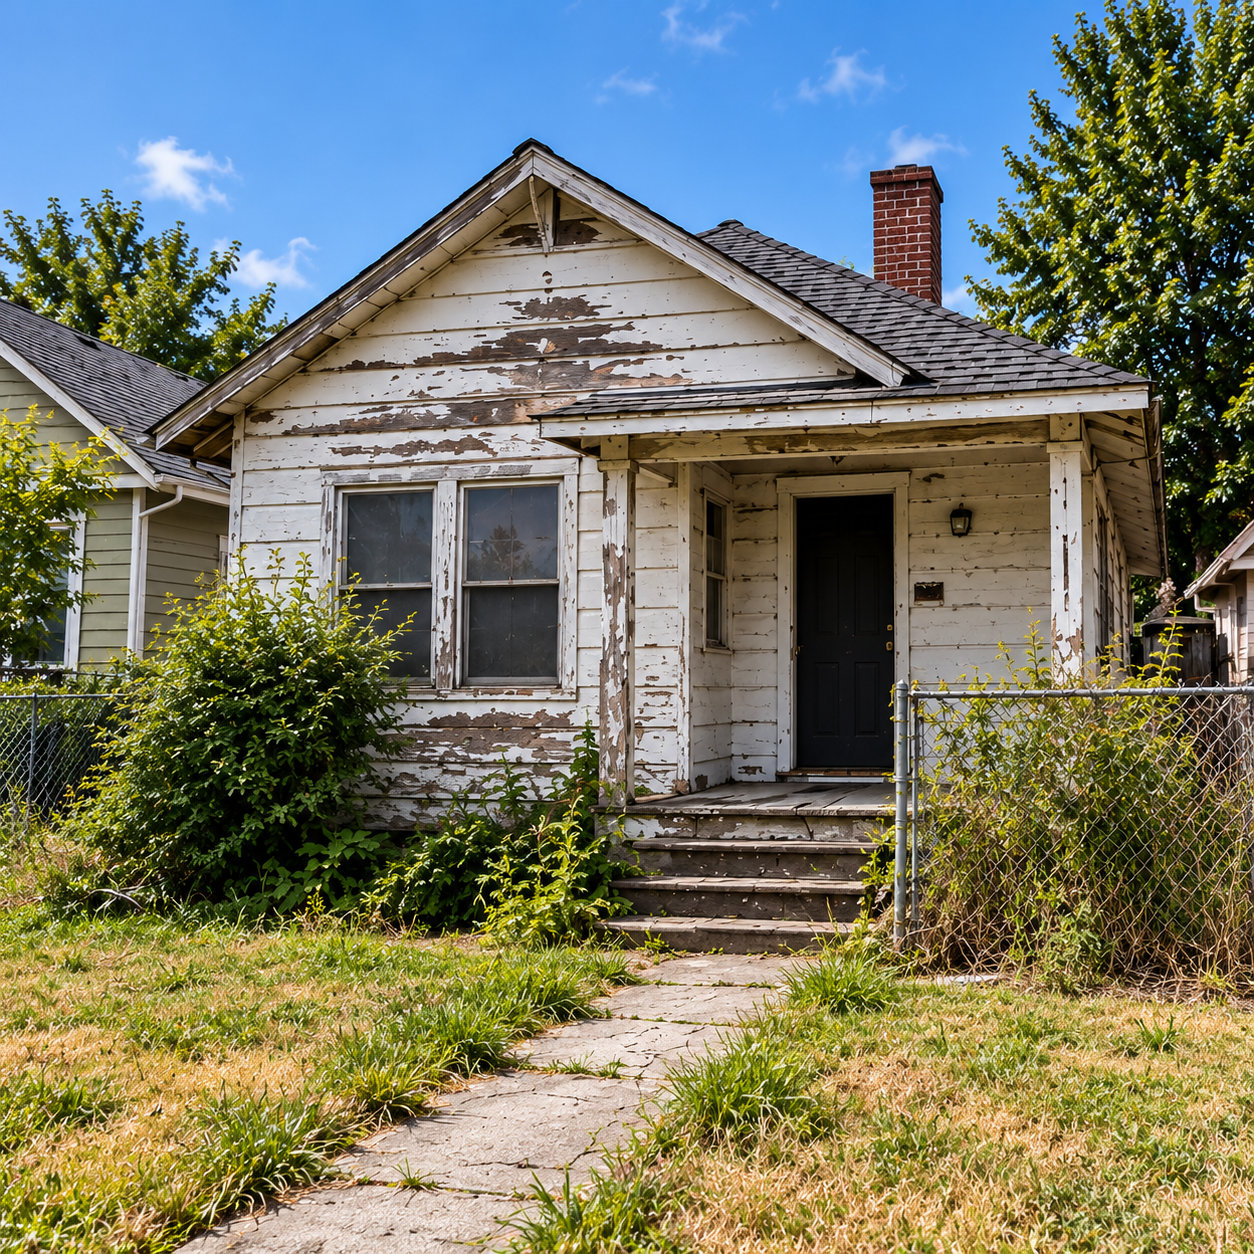
Fix-and-flip financing is commonly associated with residential investment properties that need repairs, modernization, or substantial renovation before resale.
The property’s current condition, intended improvements, location, value, and marketability after completion may all be considered.
Properties with significant condition issues that create challenges for traditional mortgage financing may sometimes be candidates for investor financing, subject to the lender’s requirements.
Fix & Flip Loans vs. Renovation Loans
Although both types of financing can involve improvements to a property, they serve very different purposes.
Fix & Flip Investor Loan
• Business-purpose financing
• Used for a non-owner-occupied investment property
• Short-term financing
• Designed around acquisition, renovation, and resale
• Evaluated partly based on the investment project and exit strategy
Renovation Mortgage
• Residential mortgage financing
• Used to purchase or improve an eligible residential property
• Structured as mortgage financing rather than a short-term flip loan
• Designed to finance eligible improvements as part of the mortgage transaction
• Subject to the requirements of the specific residential renovation program
If you are purchasing a property specifically to renovate and resell, fix-and-flip financing is the relevant category.
If you are purchasing or renovating a home as part of a longer-term residential mortgage strategy, Explore Renovation Loans →
What Is the Exit Strategy?
The exit strategy is a critical part of fix-and-flip financing because these loans are intended to be short term.
For a traditional fix-and-flip project, the expected exit is generally:
1
Purchase
2
Renovate
3
Sell
4
Repay the Fix & Flip Loan
However, investment plans can change.
An investor may ultimately decide that a renovated property makes more sense as a long-term rental rather than a sale.
If retaining the property is a possibility, the investor should consider the potential long-term financing strategy before beginning the project.
Depending on the property and borrower, long-term investment financing such as a DSCR loan may potentially provide an alternative exit strategy when appropriate.
Explore DSCR Loans →
Fix & Flip vs. BRRRR Strategy
Not every investor who purchases and renovates a property intends to sell it.
Traditional Fix & Flip
Buy → Renovate → Sell
BRRRR Strategy
Buy → Rehab → Rent → Refinance → Repeat
The initial acquisition and renovation financing may have similarities, but the intended exit is different.
An investor planning to retain the property should evaluate the potential refinance strategy before completing the acquisition whenever possible.
The ability to refinance later will depend on the property, completed value, rental income, borrower qualifications, available loan programs, and market conditions at that time.
Why Investors Use Short-Term Financing
Real estate investment transactions can require financing that works differently from a traditional mortgage.
Investors may be purchasing properties that need substantial work, competing on transaction timing, managing renovation budgets, or planning to hold the property for only a relatively short period.
Short-term investor financing is designed around those circumstances.
However, speed alone should not determine which loan is selected.
Compare the Complete Financing Structure
• Interest rate
• Origination and lender fees
• Required investor contribution
• Renovation funding
• Draw procedures
• Loan term
• Extension provisions
• Prepayment provisions, if applicable
• Reserve or liquidity requirements
• Closing timeline
• Exit strategy
The lowest advertised rate does not necessarily represent the lowest overall project cost.
Evaluating the Financing as Part of the Investment
Financing costs directly affect the economics of a fix-and-flip project.
Before moving forward, investors should consider the financing alongside:
• Acquisition cost
• Renovation budget
• Contingency funds
• Carrying costs
• Financing costs
• Property taxes and insurance
• Expected project timeline
• Estimated selling costs
• Expected resale value
• Potential profit margin
A project that appears attractive based only on purchase price and anticipated resale value can look different once renovation, financing, carrying, and transaction costs are considered.
Fix & Flip Loans in Oregon & Washington
Real estate investment opportunities vary considerably by property and market.
As an independent mortgage brokerage serving Oregon and Washington, Platinum Lending Solutions can evaluate fix-and-flip financing across multiple lending sources rather than limiting investors to a single lender or program.
That allows us to compare financing based on the specific transaction, including the acquisition, renovation budget, expected completed value, investor experience, available capital, project timeline, and exit strategy.
Whether you are completing your first investment project or regularly acquiring and renovating properties, the goal is to identify financing that fits the project rather than forcing the project into a single lending program.
Fix & Flip Loan FAQs
Is a fix-and-flip loan the same as a renovation loan?
No. Fix-and-flip loans are generally short-term, business-purpose financing for investment properties being acquired, renovated, and resold. Residential renovation loans serve a different purpose and are structured under the requirements of the applicable mortgage program.
Do I have to be an experienced real estate investor?
Not necessarily. Some lenders may consider first-time investors, while others offer different terms based on prior investment or renovation experience.
Can renovation costs be included in the loan?
Depending on the program, financing may include eligible renovation costs in addition to funds used toward the property acquisition.
What is ARV?
ARV stands for After-Repair Value. It is the estimated value of the property after the proposed renovation has been completed.
Do I receive the renovation funds at closing?
Typically, renovation funds included in the financing are controlled and released through a draw process as eligible work is completed. Procedures vary by lender.
Can I use a fix-and-flip loan for my primary residence?
Fix-and-flip loans are generally business-purpose financing for investment properties and are not intended as owner-occupied residential mortgage financing.
Can I finance a property that needs significant repairs?
Potentially. Fix-and-flip financing is designed for investment projects that may involve repairs or substantial renovation. Property eligibility varies by lender.
What happens if I decide to keep the property instead of selling it?
You would generally need to evaluate an appropriate long-term financing strategy. Depending on the transaction, a rental-property loan such as DSCR financing may potentially be an option.
How quickly do I have to complete the renovation and sell?
Loan terms and project requirements vary by lender. The expected renovation and sale timeline should be evaluated before selecting the financing.
Are fix-and-flip loan rates higher than traditional mortgage rates?
Fix-and-flip loans are a different type of financing from traditional residential mortgages. Rates, fees, terms, and qualification methods reflect the short-term and business-purpose nature of the transaction and should be evaluated based on the total project economics.
Financing Your Next Investment Project
Whether you are acquiring your first property to renovate and resell or adding another project to an established investment business, financing should be evaluated as part of the investment from the beginning.
Platinum Lending Solutions can help you compare fix-and-flip financing options and understand how the acquisition, renovation budget, leverage, draw process, and exit strategy work together.
Have Questions About Fix & Flip Financing?
Tell us a little about the property, purchase price, renovation plans, investment experience, and intended exit strategy. We can help you evaluate potential financing options and determine what may fit the project.
